It’s not just about retirement; it’s about the life you want next
A couple came to see me a while back. He was 65, she was 61. He'd always planned to retire at 65. But when it came down to it, they didn't feel ready. There ...
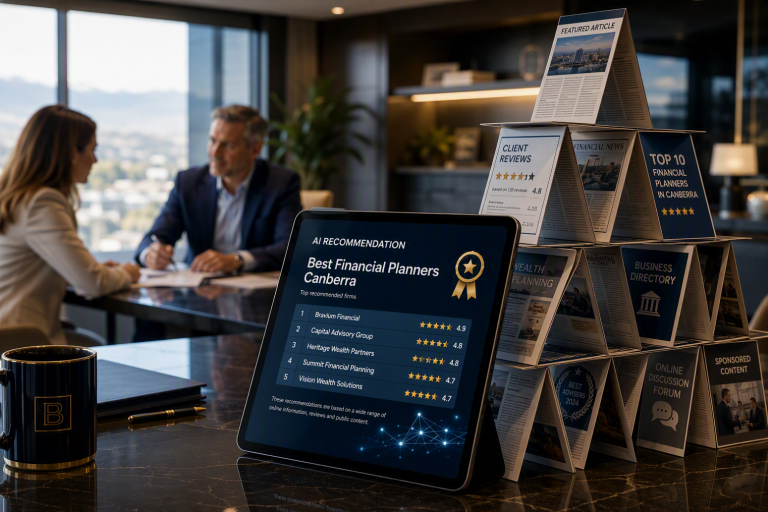
A few weeks ago, I started asking various AI tools a simple question:
“Who are the best financial planners in Canberra?”
The answers sounded remarkably confident.
They cited articles, rankings, online discussions and reviews. The recommendations looked authoritative. Well researched. Trustworthy.
Then I started following the trail.
What I discovered made me question how much evidence sometimes sits behind an answer that sounds incredibly certain.
In one case, a publication promoting a list of Canberra’s “best” businesses also openly invited businesses to express interest in being featured on future lists.
In another, recommendations appeared to be influenced by Reddit discussions that were years old and contained only a handful of comments.
None of this is necessarily deceptive.
But it raises an important question:
When AI recommends a financial planner, how much actual research sits behind that recommendation?
Many consumers imagine AI is assessing:
The reality is often much simpler.
AI is largely summarising information that already exists online.
That information may include:
The recommendation may sound authoritative, but consumers rarely see the evidence behind it.
That should matter when selecting someone who may influence your retirement, your family’s future and potentially millions of dollars over your lifetime.
Historically, search engines helped us find information.
AI increasingly attempts to provide the answer.
That is a profound shift.
When a consumer asks:
“Who is the best financial planner in Canberra?”
They aren’t presented with ten websites to evaluate themselves.
They are often presented with a shortlist.
The recommendation arrives neatly packaged and confidently delivered.
Most people naturally assume that confidence is backed by extensive research.
But confidence and evidence are not the same thing.
Recently I explored several articles ranking the “best financial planners” in Canberra.
At first glance they appeared authoritative.
Exactly the sort of content that AI systems would use when forming recommendations.
Then I found something that stopped me in my tracks.
One publisher openly promoted opportunities for businesses to be featured in its “best of” listings.
The marketing material discussed:
In other words, visibility.
The article talks about the “best” businesses.
The sales page talks about advertising opportunities.
Those are not necessarily the same thing.
To be clear, there is nothing inherently wrong with advertising.
There is nothing inherently wrong with sponsored content.
There is nothing inherently wrong with publishers generating revenue.
The issue is what happens when AI encounters that content.
AI may see a respected publication mentioning a financial planning firm and treat that as an authority signal.
But should a commercial placement carry the same weight as an independent assessment?
More importantly:
Does the consumer understand the difference?
Because I suspect many don’t.
Then there is Reddit.
AI systems love Reddit because it contains real conversations from real people.
That sounds reasonable until you look more closely.
Some recommendations appear to be influenced by discussions that are years old and contain only a handful of comments.
Think about that.
A consumer searching for a financial planner in 2026 may receive recommendations influenced by a discussion from several years ago involving only a few anonymous contributors.
That isn’t comprehensive research.
That isn’t an industry review.
It’s simply a conversation that happened to be indexed by search engines.
Yet it may still become a meaningful signal in an AI-generated recommendation.
This is the part I find most fascinating.
And perhaps most concerning.
Consumers assume AI recommendations are built on vast amounts of evidence.
Hundreds of independent assessments.
Broad industry consensus.
Extensive research.
But sometimes the trail appears surprisingly thin.
A single article.
A directory listing.
A handful of reviews.
A Reddit discussion involving only a few people.
A local award.
Individually, none of these sources may represent compelling evidence that a business is genuinely “the best”.
Yet an AI system can aggregate these fragments into an answer that sounds extraordinarily certain.
The problem isn’t necessarily that AI gets the answer wrong.
The problem is that consumers often don’t know how little evidence may sit behind an answer that sounds incredibly certain.
Consumers see the answer.
They rarely see how the answer was formed.
If AI recommends a restaurant that turns out to be average, that’s inconvenient.
If AI recommends a movie you don’t enjoy, you’ve lost a couple of hours.
Choosing a financial adviser is different.
The adviser you select may influence:
These decisions can affect hundreds of thousands, or even millions, of dollars over a lifetime.
Surely we should expect more evidence than a sponsored article, a directory listing and a few online comments.
Ironically, the answer is remarkably low-tech.
Use AI to create a list, and ask friends, family and work colleagues for a recommendation.
Then do your own homework.
A firm’s website won’t tell you whether they are a great adviser.
But it can tell you something about the business.
Ask yourself:
A website is often one small reflection of the broader client experience.
Businesses that obsess over client experience tend to think carefully about every touchpoint, including their website, communication, onboarding process and ongoing service.
Businesses that pay attention to detail rarely leave obvious weak links in the chain.
A website should never be the deciding factor.
But it can be a useful filter.
This is where the real assessment begins.
A ten-minute conversation with an adviser will often tell you more than hours of online research.
Can they explain what they do?
Can they articulate who they help?
Can they explain complex concepts clearly?
Can they demonstrate a genuine understanding of your situation?
Do they ask thoughtful questions?
Do they make sense?
Do you trust them?
If an adviser cannot clearly communicate their value, process and expertise during a short introductory conversation, that should raise questions.
After all, if they struggle to explain their thinking during an introductory call, how will they explain the financial decisions that could shape your future?
Financial advice is ultimately a relationship business.
And relationships are difficult to evaluate through search results, online rankings and AI-generated recommendations.
AI is changing the way consumers search.
That isn’t going away.
Nor should it.
AI can be an excellent tool for discovering businesses and gathering information.
But when it comes to something as important as your financial future, consumers should remain curious about the evidence sitting behind the recommendation.
Because the most important question is no longer:
“Who does AI recommend?”
The more important question is:
“Why does AI recommend them?”
The answer may have less to do with expertise than most people realise.
And when your retirement, your family’s future and your life savings are at stake, that’s a distinction worth understanding.
A good financial planner doesn’t need to be the most mentioned online. They need to be the right adviser for you. No algorithm can determine that. Only a conversation can.
A couple came to see me a while back. He was 65, she was 61. He'd always planned to retire at 65. But when it came down to it, they didn't feel ready. There ...

Samantha from Bravium has been shortlisted for the prestigious Young Leaders in Finance Awards.

The Royal Commission into Misconduct in the Banking, Superannuation and Financial Services Industry was established on 14 December 2017, with a final report due by 1 February 2019.